
Filling in your VAT return
This page explains how to fill in the various boxes in your VAT return.
A – VAT taxable sales or withdrawals excluding VAT
The amounts entered in boxes 05–08 must relate to the same reporting period as the VAT amounts entered in boxes 10–12.
Box 05 – VAT taxable sales not reported in box 06, 07 or 08
Here you report your VAT taxable sales of goods and services in Sweden, excluding VAT. You must also report sales of equipment for which you were entitled to a VAT deduction, or for which VAT was refunded to you.
You must report certain sales you make to other EU countries
Sales made to customers in other EU countries can be subject to VAT in Sweden. If so, you must report them in box 05. Such a sale might be subject to VAT in Sweden if the customer:
- is not registered for VAT (this applies if the buyer is a private individual); or
- is a business that does not have a valid VAT number
Confirmed customer loss
If you report a reduced output VAT amount for reasons such as a confirmed customer loss, price reduction or return, you must also report a reduced sales amount in this box.
Customer loss: buyer non-payment (in Swedish) External link.
Exceptions: VAT margin scheme and rental income
- Report sales subject to the VAT margin scheme in box 07
- Report rental income subject to voluntary VAT liability in box 08.
Box 06 – VAT taxable self-supply
Enter the value of goods and services that are subject to VAT on self-supply, excluding VAT.
VAT on self-supply for private use (in Swedish) External link.
Goods
You are liable for VAT on self-supply if, without receiving compensation, you:
- withdraw goods from your business for private use
- give goods away
- transfer goods to a non-VAT-liable business operation.
Services
You are liable for VAT on self-supply if, without receiving compensation, you:
- use a business asset for private purposes
- allow someone else to use a business asset
- supply, or arrange for the supply of, a service for the benefit of yourself, your staff, or some other party.
Certain real-estate services are subject to special VAT rules on self-supply.
Revaluation
If you adjust the taxable amount for a transaction made below or above the open market value, you must also report this here – even if the transaction does not constitute a self-supply.
Box 07 – Taxable amout under the VAT margin scheme
Enter the taxable amount for sales of goods and travel services under the VAT margin scheme. The taxable amount is the amount on which VAT is calculated. If the profit margin is negative, enter SEK 0.
Second-hand goods, works of art, collector's items and antiques
The taxable amount is the profit margin on the sale of the above goods, minus the VAT on that profit margin. The profit margin is the difference between the sale price and the purchase price of goods. If you're permitted to use the simplified VAT margin scheme, the profit margin is the difference between total sales revenue and the total purchase costs associated with such goods during a particular reporting period.
Travel services
When a travel service is sold under the VAT margin scheme, the taxable amount is equal to the travel business’s profit margin excluding VAT. The profit margin is the difference between the price of the trip (including VAT) and the travel business’s costs (including VAT) associated with goods and services that are included in the travel service, and which directly benefit the traveller.
Box 08 – Rental income subject to voluntary VAT liability
Here you report rental income, excluding VAT, from properties for which you have opted for voluntary VAT liability for the rental of business premises.
Property rental and voluntary VAT liability (in Swedish) External link.
B – Output VAT on sales or self-supply reported in boxes 05–08
Box 10 – Output VAT 25%
Box 11 – Output VAT 12%
Box 12 – Output VAT 6%
Enter the output VAT amount for each VAT rate on:
- sales of goods and services in Sweden (including rental income subject to voluntary VAT liability, and sales for which VAT is calculated on the profit margin)
- withdrawals of goods and services
- advance payment for goods or services ordered from you by customers in Sweden.
C – VAT taxable purchases subject to reverse charge liability
In this section, you report purchases for which you are required to calculate and report the output VAT as the buyer. This section is only applicable to such purchases under special rules, such as the VAT reverse charge mechanism. Do not report ordinary purchases made in Sweden, where the seller is required to add VAT to the invoice.
Reverse charge VAT liability (in Swedish) External link.
Box 20 – Intra-EU acquisition of goods
Enter the value of goods you have purchased from sellers in other EU countries and transported to:
- Sweden; or
- another EU country, if you provided your VAT number (see the exception below).
You must also report the value of transfers (cross-border transportation of goods) to Sweden from your business operations in other EU countries, if these transfers are subject to VAT in Sweden.
Non-Swedish businesses must also report the value of transfers from their business operations in other EU countries, even if these transfers are not subject to VAT in Sweden. This applies to non-Swedish businesses that are registered for VAT in Sweden because they make intra-EU acquisitions that are exempt from VAT.
Exception
Do not report goods you have purchased for direct resale as an intermediary in a triangulation transaction in this box. Report such purchases in box 37 instead. A triangulation transaction is where a seller in one EU country sells goods to a buyer (the intermediary) in another EU country, but the goods are delivered directly to a customer in a third EU country. All three parties must be registered for VAT in their respective countries.
Box 21 – Services purchased from other EU countries under the general rule
Here you report the value of services purchased from sellers in other EU countries, provided that the general rule is applicable and you are liable to report and pay the output VAT as the buyer. Under the general rule, such services are considered to have been supplied in Sweden. This applies to most VAT taxable services, with the following exceptions:
- real-estate services
- passenger transport
- admission to cultural, artistic, sporting, scientific, educational, entertainment and similar events
- restaurant and catering services
- short-term hire of means of transport.
Report the purchase of certain real-estate services to which the general rule does not apply in box 24 instead. The same principle for distinguishing between different types of services also applies to boxes 39 and 40.
Box 22 – Services purchased from non-EU countries
Here you report the value of services purchased from sellers in non-EU countries if the general rule is applicable and you are liable to report and pay the output VAT as the buyer.
Services to which the general rule does not apply are listed below box 21.
Report the purchase of certain real-estate services to which the general rule does not apply in box 24 instead.
Box 23 – Goods purchased in Sweden subject to reverse charge VAT
Enter the value of goods purchased in Sweden on which you are liable to report and pay the output VAT as the buyer.
Examples of goods purchases subject to reverse charge VAT include:
- goods purchased in Sweden from a foreign business that has not requested to be liable for VAT on sales to VAT-registered buyers in Sweden
- gold material or semi-finished products with a fineness of at least 325 parts per thousand
- investment gold, if the seller has voluntary VAT liability for the sale
- gas, electricity, heating or cooling purchased from a non-Swedish business on which you, as a reseller or consumer in Sweden, are liable to pay VAT
- waste and scrap of certain metals
- mobile phones, integrated circuit devices, games consoles, tablet computers and laptops, if the total taxable amount stated on the invoice for such goods exceeds SEK 100,000.
Here you also report the value of goods removed from an excise warehouse or customs warehouse, and the value of services relating to these goods, if VAT liability arises from their removal.
Box 24 – Other services purchased in Sweden subject to reverse charge VAT
Enter the value of services other than those you're required to report in box 21 or 22, on which you are liable to report and pay the output VAT as the buyer. Examples of service purchases subject to reverse charge VAT include:
- building and construction sector services for which you must report and pay VAT, as the buyer, under the reverse charge mechanism (this also applies if you sell a building/construction service to a party that sells building/construction services)
- certain services relating to real estate in Sweden, which are supplied by a foreign business that has not requested to be liable for VAT on sales to VAT-registered buyers in Sweden
- greenhouse gas emissions allowances.
D – Output VAT on purchases reported in boxes 20–24
Box 30 – Output VAT 25%
Box 31 – Output VAT 12%
Box 32 – Output VAT 6%
Enter the output VAT amount for each VAT rate on purchases reported in boxes 20 to 24. You must calculate the output VAT and enter the amount in box 30, 31 or 32, depending on the VAT rate that applies.
You must report output VAT on the purchase of:
- goods from other EU countries
- services from sellers in other EU countries
- services from sellers in countries outside the EU
- goods supplied in Sweden which are subject to reverse charge VAT
- services supplied in Sweden which are subject to reverse charge VAT.
E – VAT-exempt sales and other transactions
In this section you report sales on which you must not charge Swedish VAT.
Box 35 – Goods sold to other EU countries
Report the following:
- The invoiced value of your VAT-exclusive sales of goods to a customer in another EU country – if the customer has provided a valid VAT number issued by an EU country other than Sweden and the goods are transported out of Sweden. You must not report advance payment for such goods until they have been delivered.
- The acquisition cost of goods transferred to your own branch or business operation in another EU country – if that branch or business operation is registered for VAT there. Goods transfer refers to the cross-border transport of goods within the EU with no change of ownership.
Exception
You must not report the value of goods transfers to another EU country if the goods are considered to have been supplied in return for compensation in that country in connection with installation or assembly services. You must report supplies with installation or assembly services in box 42.
EC sales list
You must also report the buyer’s valid VAT number, and state the amount entered in box 35, in an EC sales list (recapitulative statement).
EC sales list (recapitulative statement) for goods and services
Box 36 – Goods sold outside the EU
Enter the value of goods you sell outside the EU, including the following, for example:
- goods directly exported to a place outside the EU
- goods collected by a foreign business for direct export to a place outside the EU
- goods supplied to duty-free shops
- temporarily registered cars and motorcycles
- cars and motorcycles supplied outside the EU
- goods sold to individuals living outside the EU (duty-free sales).
You must also report the following here:
- The value of goods that you transfer from Sweden to countries outside the EU. If you then sell the goods outside the EU, you must not report that sale in your VAT return.
- Advance payment for goods ordered for export. Report an advance payment during the period in which you receive it.
You can also report sales of goods here if:
- you purchase goods in another EU country, and they are delivered to a country outside the EU
- you purchase goods in a country outside the EU, and they are delivered to another country outside the EU.
Selling goods to countries outside the EU: exports
Box 37 – Goods purchased as an intermediary in a triangulation transaction
Here you report goods that you have purchased for direct resale from VAT-registered sellers in EU countries other than Sweden. In such cases, you are acting as the intermediary in a triangulation transaction. A triangulation transaction is where a seller in one EU country sells goods to a buyer (the intermediary) in another EU country, but the goods are delivered directly to a customer in a third EU country. All three parties must be registered for VAT in their respective countries. As the intermediary, you do not pay VAT on the triangulation acquisition. This is an exception to standard intra-EU acquisitions, which you must report in box 20.
Box 38 – Goods sold as an intermediary in a triangulation transaction
Here you report sales to VAT-registered buyers in EU countries other than Sweden, of goods you have purchased as an intermediary in a triangulation transaction. A triangulation transaction is where a seller in one EU country sells goods to a buyer (the intermediary) in another EU country, but the goods are delivered directly to a customer in a third EU country. All three parties must be registered for VAT in their respective countries.
EC sales list
You must also report the amount you have entered in box 38 as the value of triangulation transactions in an EC sales list (recapitulative statement).
EC sales list (recapitulative statement) regarding goods and services
Box 39 – Services sold to taxable persons in other EU countries under the general rule
Here you report the value of services sold exclusive of VAT to taxable persons in other EU countries when the general rule is applicable. Under the general rule, these services are considered to be supplied in the other EU country. The buyer is liable to pay VAT on their purchase.
The general rule is applicable to most VAT taxable services. The exceptions are:
- real-estate services
- passenger transport services
- admission to cultural, artistic, sporting, scientific, educational, entertainment and similar events
- restaurant and catering services
- short-term hire of means of transport.
Report sales of services that are not covered by the general rule, and are supplied outside Sweden, in box 40 instead.
Sales of services that are exempt from VAT in Sweden should be reported in box 42.
EC sales list
You must also report the value of your services sales in an EC sales list (recapitulative statement), provided that the purchaser has a valid VAT number and the services are subject to VAT in the other EU country in question. If a sale does not match these criteria, you must not report it in an EC sales list, since this would be inconsistent with the details reported in your VAT return.
EC sales list (recapitulative statement) regarding goods and services
Box 40 – Other sales of services supplied abroad
Here you report other sales of services supplied outside Sweden that must not be reported in box 39. Examples include:
- services to which the general rule is not applicable, which you sell to taxable persons in other EU countries (services to which the general rule applies must be reported in box 39 instead)
- services such as intermediary services, transport and work carried out on movable property, sold to buyers in other EU countries who are not taxable persons
- services sold to buyers in countries outside the EU
- travel services outside Sweden if the VAT margin scheme is not applicable (if the VAT margin scheme is applicable, report the taxable amount in box 07 instead).
Report sales of services that are exempt from VAT in Sweden in box 42.
If you use the OSS e-service to report sales of digital services to non-taxable persons in other EU countries, do not report these sales again in your regular VAT return.
Report and pay VAT through the One Stop Shop
Box 41 – Sales for which the buyer is liable to pay VAT in Sweden
Here you report sales in Sweden on which the buyer must report and pay the VAT (i.e. sales subject to reverse charge VAT) Examples of such sales include:
- building/construction services for which the buyer must report and pay the VAT
- goods and certain real-estate services sold by a non-Swedish business to VAT-registered customers in Sweden, if the non-Swedish business has not requested to be liable for VAT on the sale
- gold material or semi-finished products with a fineness of at least 325 parts per thousand
- investment gold, if the seller has voluntary VAT-liability for the sale (although, as the seller, you have voluntary VAT-liability for the sale, the buyer must still report and pay the VAT)
- greenhouse gas emissions allowances
- waste and scrap of certain metals
- mobile phones, integrated circuit devices, games consoles, tablet computers and laptops, if the total taxable amount stated on the invoice for such goods exceeds SEK 100,000.
Box 42 – Other sales and transactions
Here you report VAT-exempt sales that must not be reported in any other box. Also report insurance compensation and subsidies that do not constitute payment for goods or services.
Examples of such sales and transactions include:
- goods supplied with installation or assembly services (note that goods meeting the exception criteria specified under box 35 must be reported here)
- VAT-exempt rental of property
- fixed assets, such as cars, for which you were not entitled to claim a VAT deduction on purchase
- prescription medicines
- new means of transport sold to buyers in other EU countries that are not taxable persons (private individuals, for example)
- gasoline-type and kerosene-type jet fuel
- ships for use in commercial shipping and commercial fishing
- certain membership newsletters and periodicals
- VAT-exempt gaming activities
- investment gold, if you do not have voluntary VAT-liability for the sale
- gas, electricity, heating or cooling supplied to non-Swedish resellers that are liable to pay VAT, or to parties that consume these outside Sweden and are liable to pay VAT on their purchase.
Examples of subsidies include:
- certain EU subsidies
- business subsidies
- reorientation support
- electricity support.
EC sales list
In some cases, you must also submit an EC sales list (recapitulative statement) for services that are exempt from VAT when supplied in Sweden. This is the case if the general rule is applicable to these services, and the purchaser is a taxable person established in an EU country where the services are subject to VAT. Examples include:
- transport of certain goods
- fees paid to artists and performers.
H – Imports
Box 50 – Taxable amount for imports
Here you report the taxable amount for the VAT payable on imports. Leave this box blank if no VAT is payable, for example because the imported goods are exempt from VAT.
The taxable amount is calculated based on the customs value in Swedish kronor; customs duty and other state charges; plus incidental expenses such as commission, packaging, insurance and transport to the known place of destination stated in the international transport document.
Purchasing goods from non-EU countries
I – Output VAT on imports reported in box 50
Box 60 – Output VAT 25%
Box 61 – Output VAT 12%
Box 62 – Output VAT 6%
Here you report output VAT on the taxable amount for imports, at each VAT rate. You must calculate the output VAT and enter the amount in box 60, 61 or 62, depending on the applicable VAT rate.
F – Input VAT
Box 48 – Input VAT to deduct
Here you report deductible input VAT (VAT you have paid on purchases). This includes VAT on:
- goods and services you have purchased in Sweden
- goods you have imported
- services you have purchased from countries outside the EU
- goods and services you have purchased from other EU countries.
You must not claim a deduction for foreign VAT in your VAT return. In some cases, you may be able to claim a refund from the tax authority in the country in question. You may also be able to claim a VAT deduction for purchases in Sweden – even if you are required to report the output VAT in another country.
Foreign VAT refunds (in Swedish)
Deducted VAT amount to repay
Only fill in this box if the amount of VAT to repay exceeds your deductible input VAT. This may be the case if you have received credit notes, for example.
This box is only available in the "File a VAT return" e-service.
G – VAT to pay or reclaim (must be completed)
Box 49 – VAT to pay or reclaim
Enter the amount of VAT you must pay or can reclaim for the period. This is the sum of the amounts you have entered in boxes 10, 11, 12, 30, 31, 32, 60, 61 and 62, minus the amount in box 48. You must enter an amount in box 49.
No VAT to report for this period
If you have no VAT to report for this period, do one of the following:
- click “Deklarera noll” (“Report zero”) in the e-service
- enter 0 in box 49 on your paper VAT return.
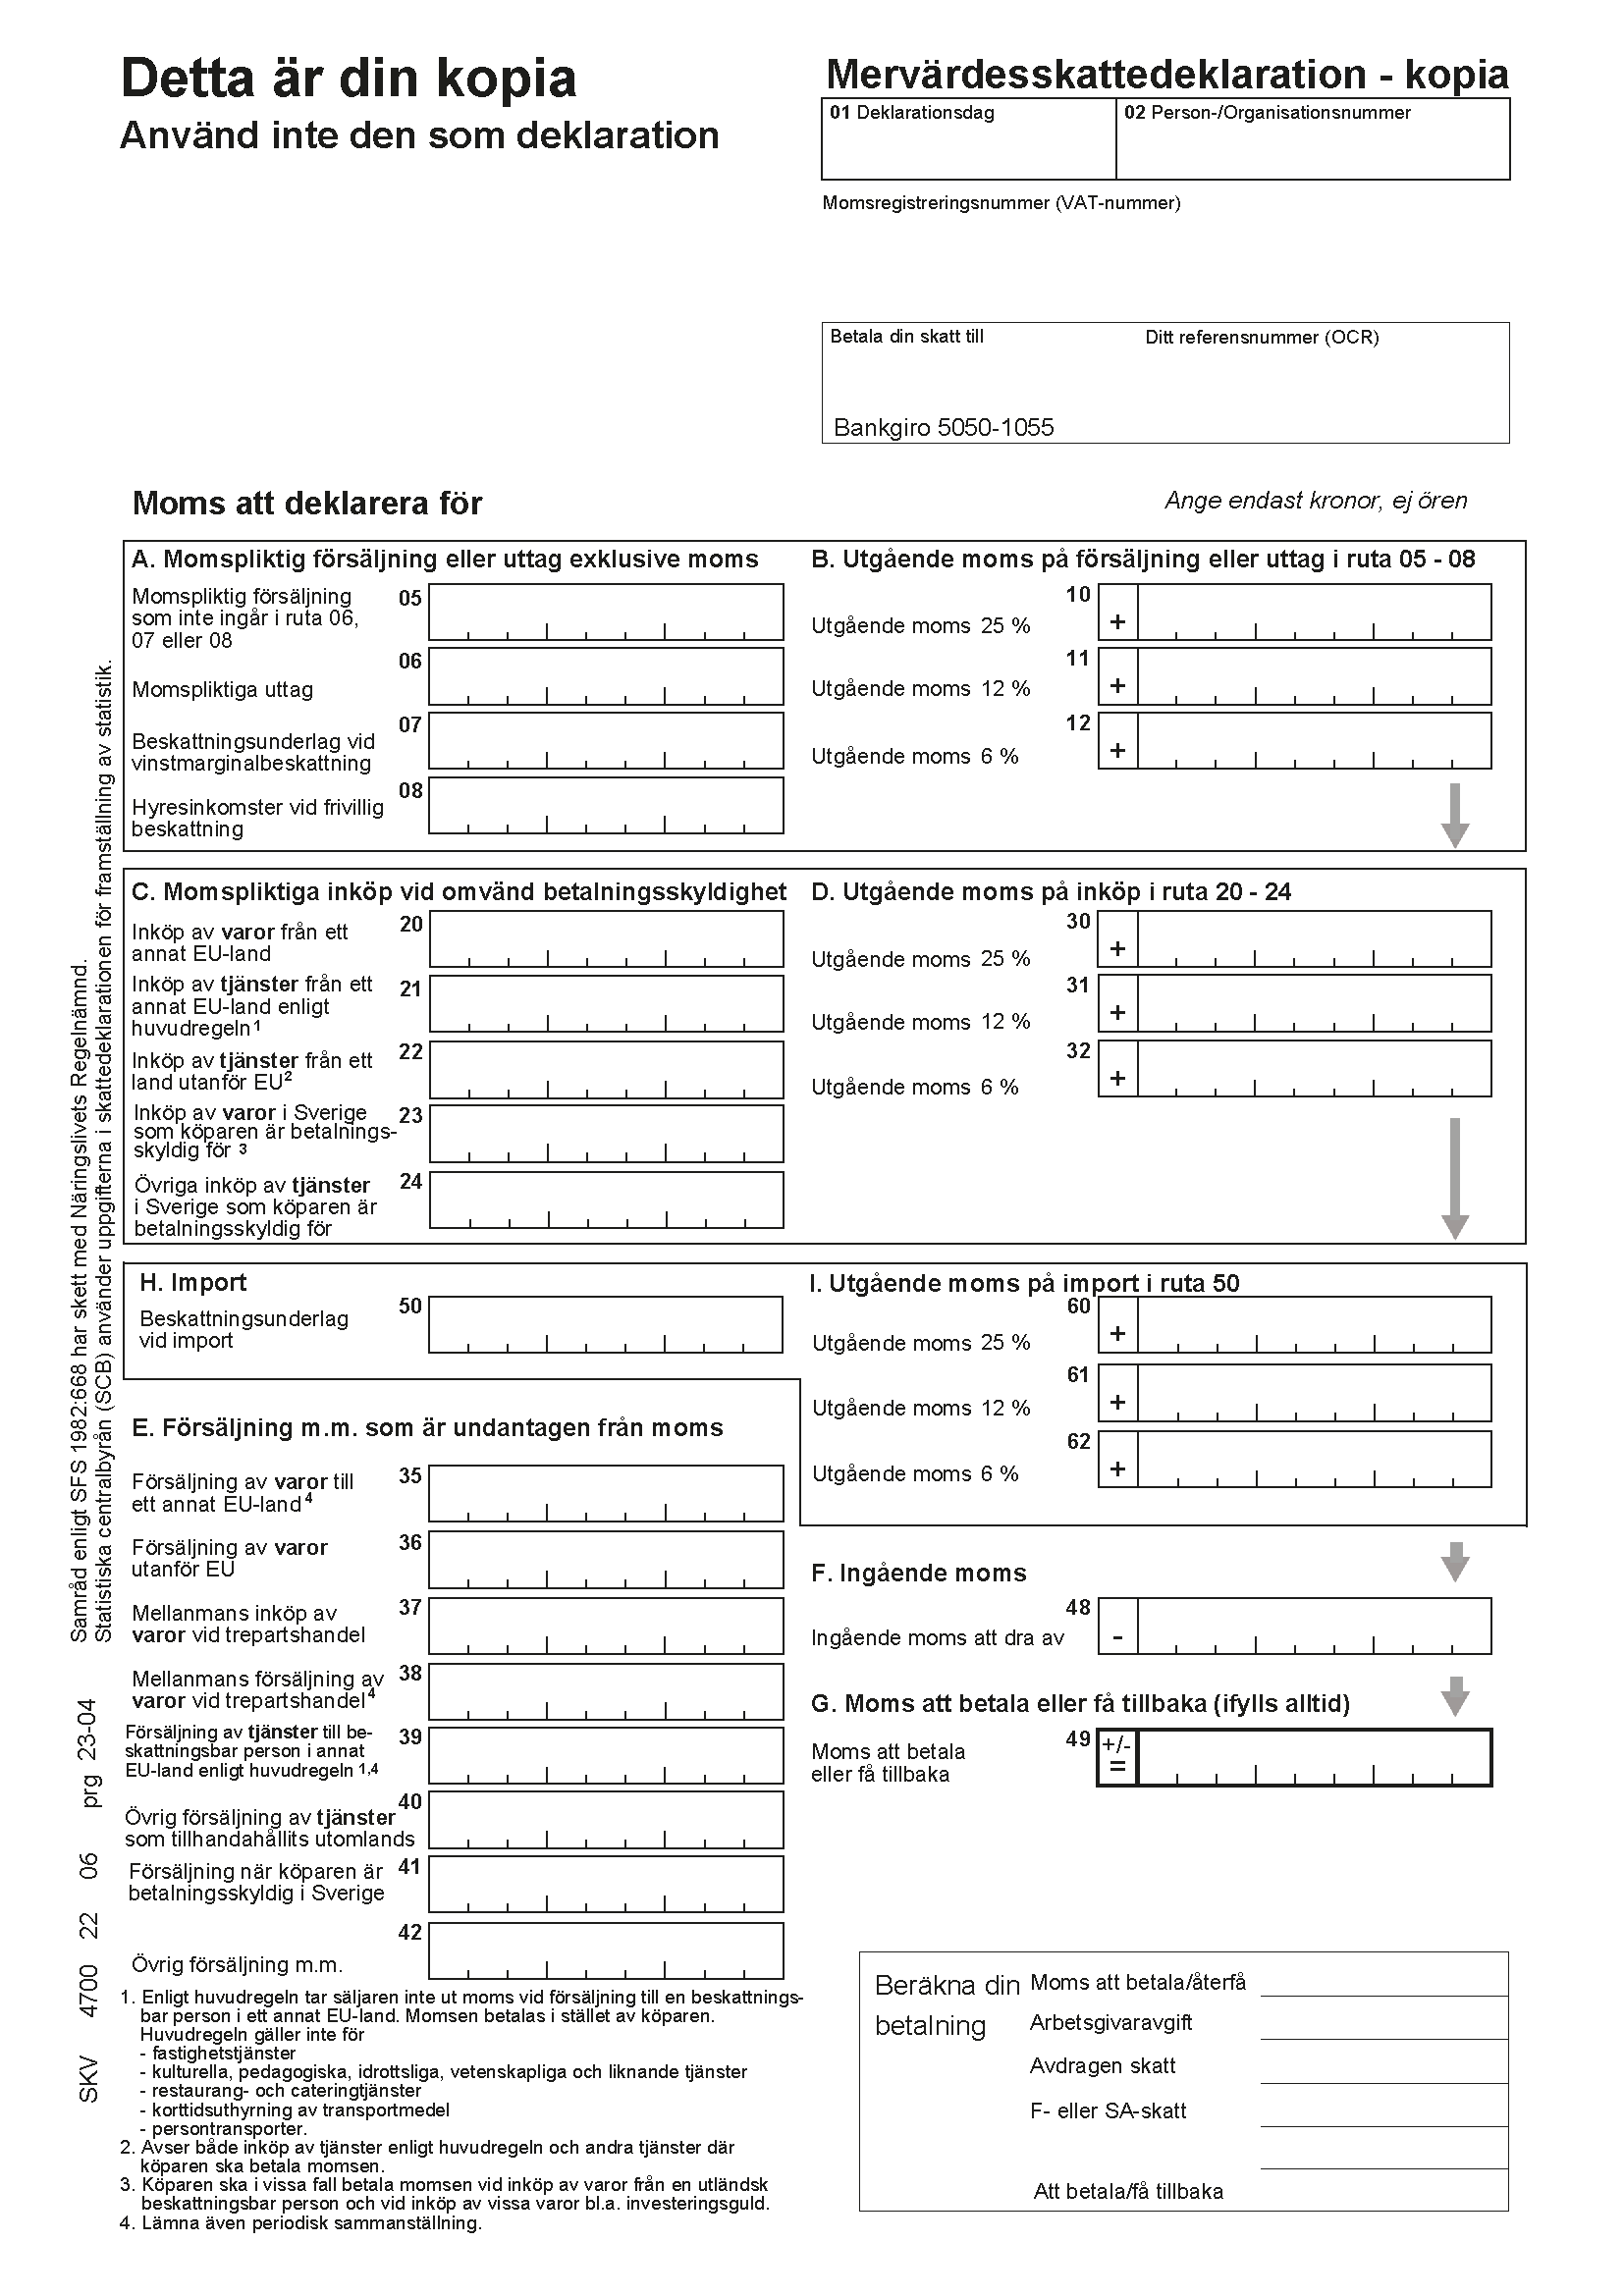
This is what a paper VAT return looks like
The image illustrates what a paper VAT return looks like Further information about how to file a VAT return is available here: